

Stock News Highlights
Pace Digitek (+8.32%): Shares advanced after its subsidiary Lineage Power (LPPL) secured a ₹488.46 crore order from NTPC GE Power Services for a BESS project at Barh STPP (NTPC Stages I & II).
Garden Reach Shipbuilders & Engineers (+1.16%): Shares rose after the Board approved a ₹2,896 crore capital outlay for a greenfield shipyard at Raichak, aimed at expanding its naval and commercial shipbuilding capacity.
Waaree Energies (-0.17%): Shares remained unchanged after the company received an order from a leading solar developer for the supply of 2 GW of solar modules.
Pine Labs (+2.00%): Shares rose despite reports that Mastercard Asia/Pacific may sell its entire 4.3% stake in the company through a block deal at a floor price of ₹179.50 per share.
Sectoral Performance
Nifty Media (+1.21%): The index advanced as investors shifted away from heavyweight IT stocks amid a sharp sell-off, with buying interest moving toward relatively undervalued pockets, led by Sun TV Network, Prime Focus & Saregama India.
Nifty Realty (+0.90%): The index advanced for the fifth consecutive session, supported by sustained buying interest across realty stocks and expectations of strong housing demand, with 9 gainers & 1 loser.
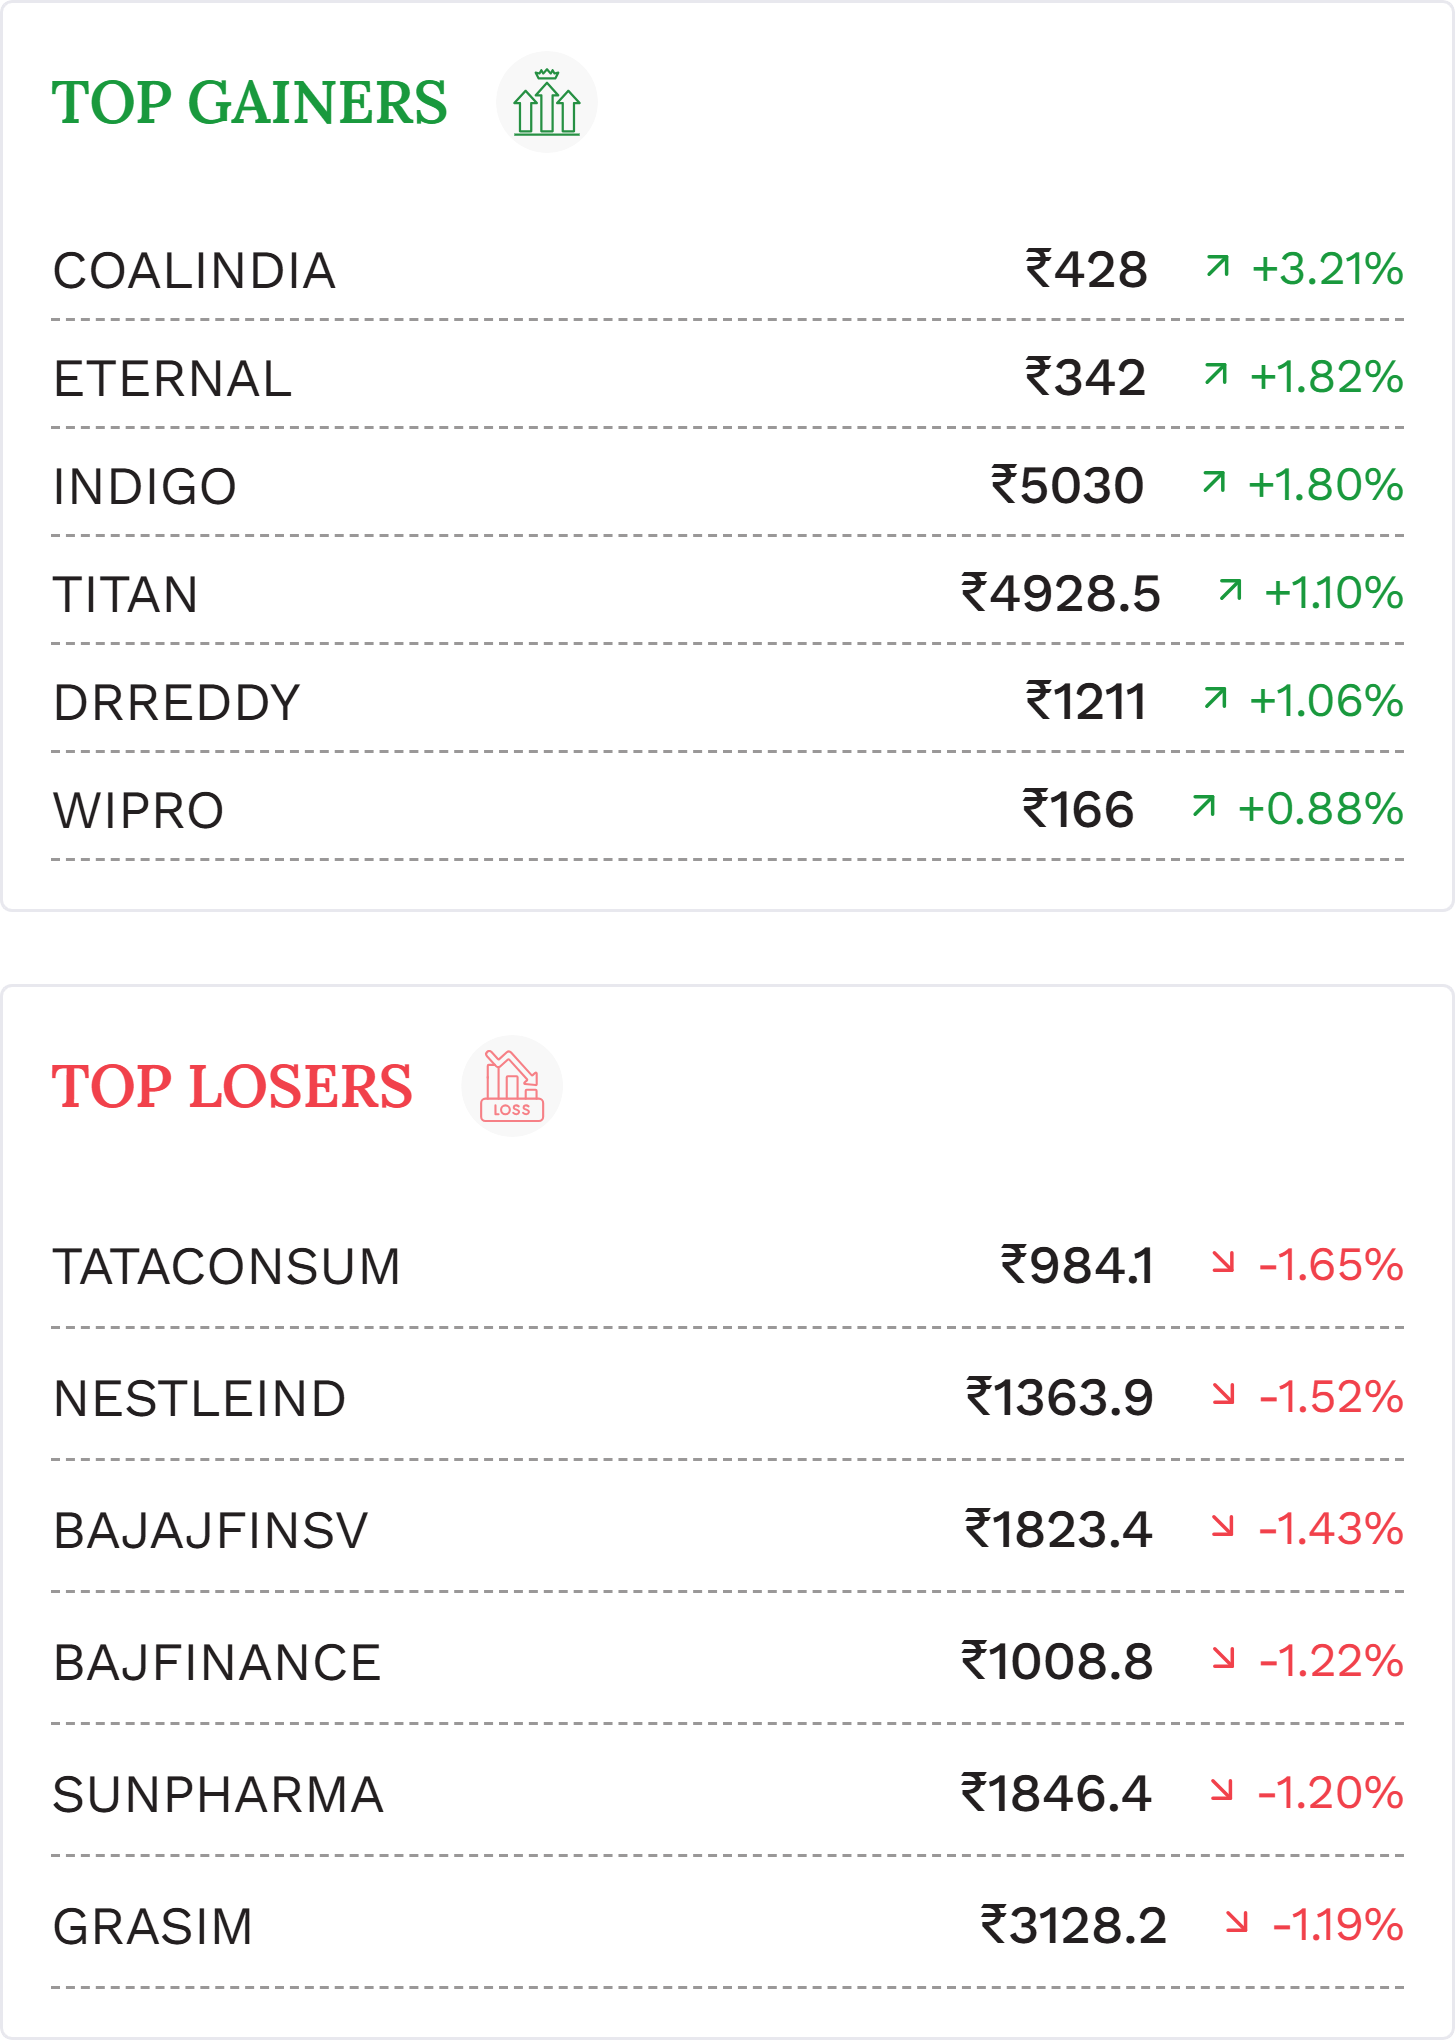
Nifty IT (-0.86%): The index emerged as the worst-performing sector, extending its decline for the third consecutive session as elevated US yields, muted discretionary tech spending and cautious demand commentary weighed on sentiment. LTM, Infosys and TCS were among the major losers. CLSA also flagged subdued demand and earnings downside risks for the sector amid geopolitics, higher rates and inflation.
Nifty Consumer Durables (-0.64%): The index declined amid broad-based profit booking and selling pressure across consumer durable stocks, with 2 gainers & 13 losers, as investors remained cautious following recent gains.
Market Insights
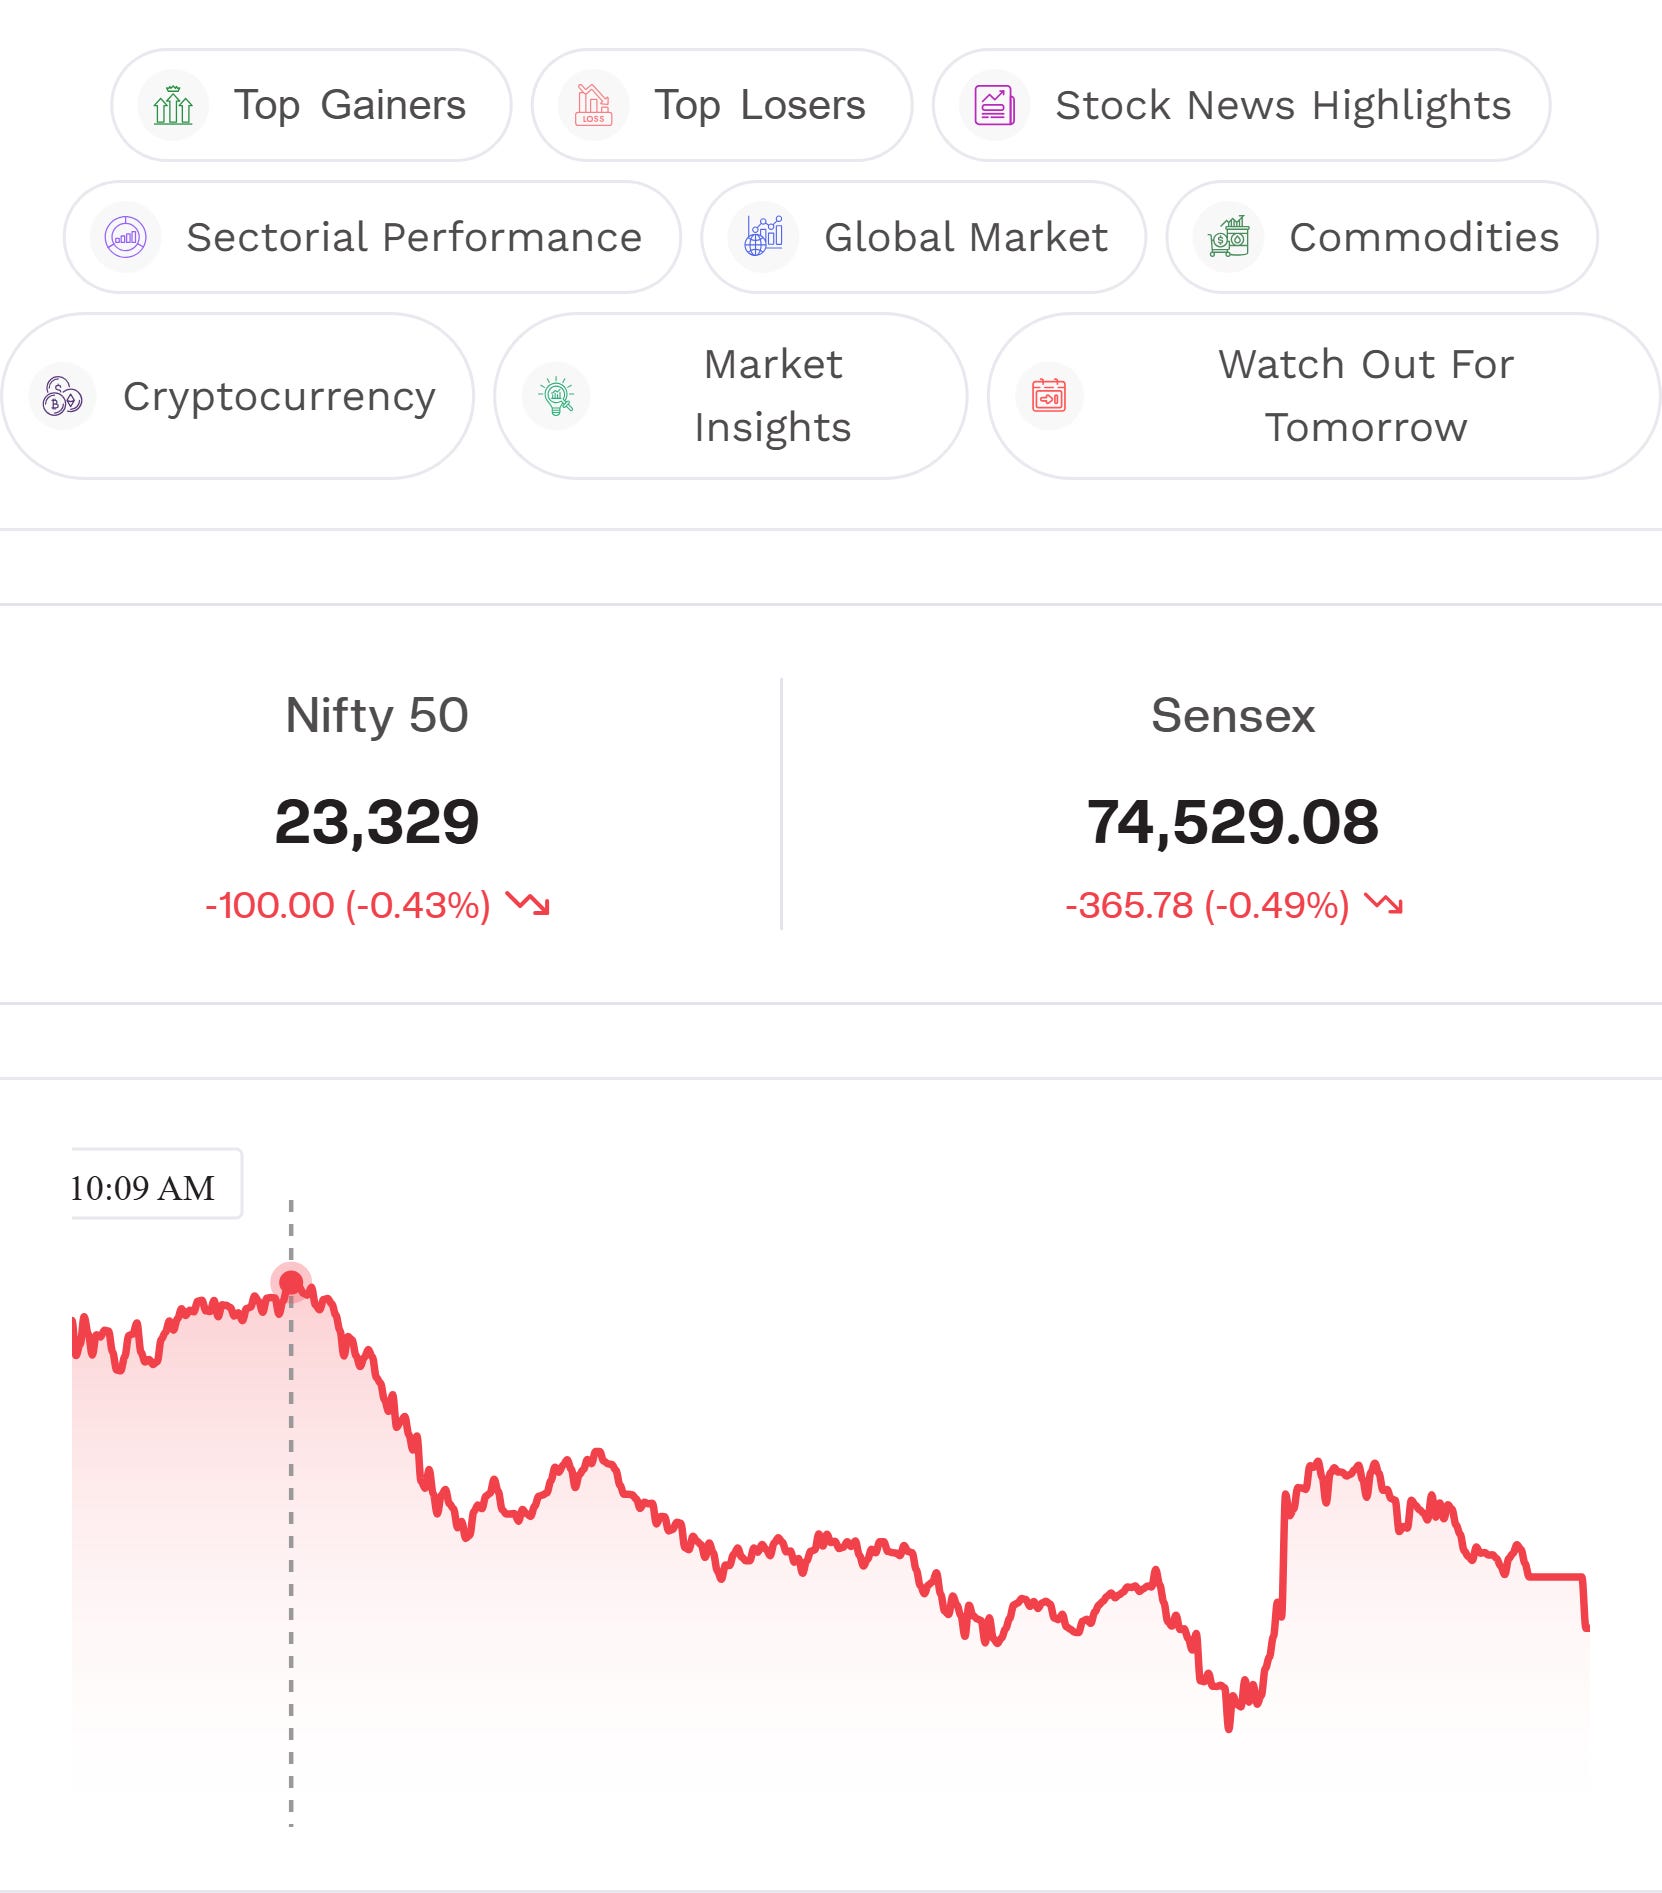
Technical Level: Nifty opened with a gap-up but traded in a narrow range, facing resistance near 23,490 before falling sharply toward the start of the second half. The index found support around 23,490 and recovered marginally, but remained in negative territory overall.
Advance-Decline Ratio: Market breadth remained negative, with 1,677 stocks advancing against 1,867 declining, resulting in an A/D ratio of 0.90, indicating broader selling pressure.
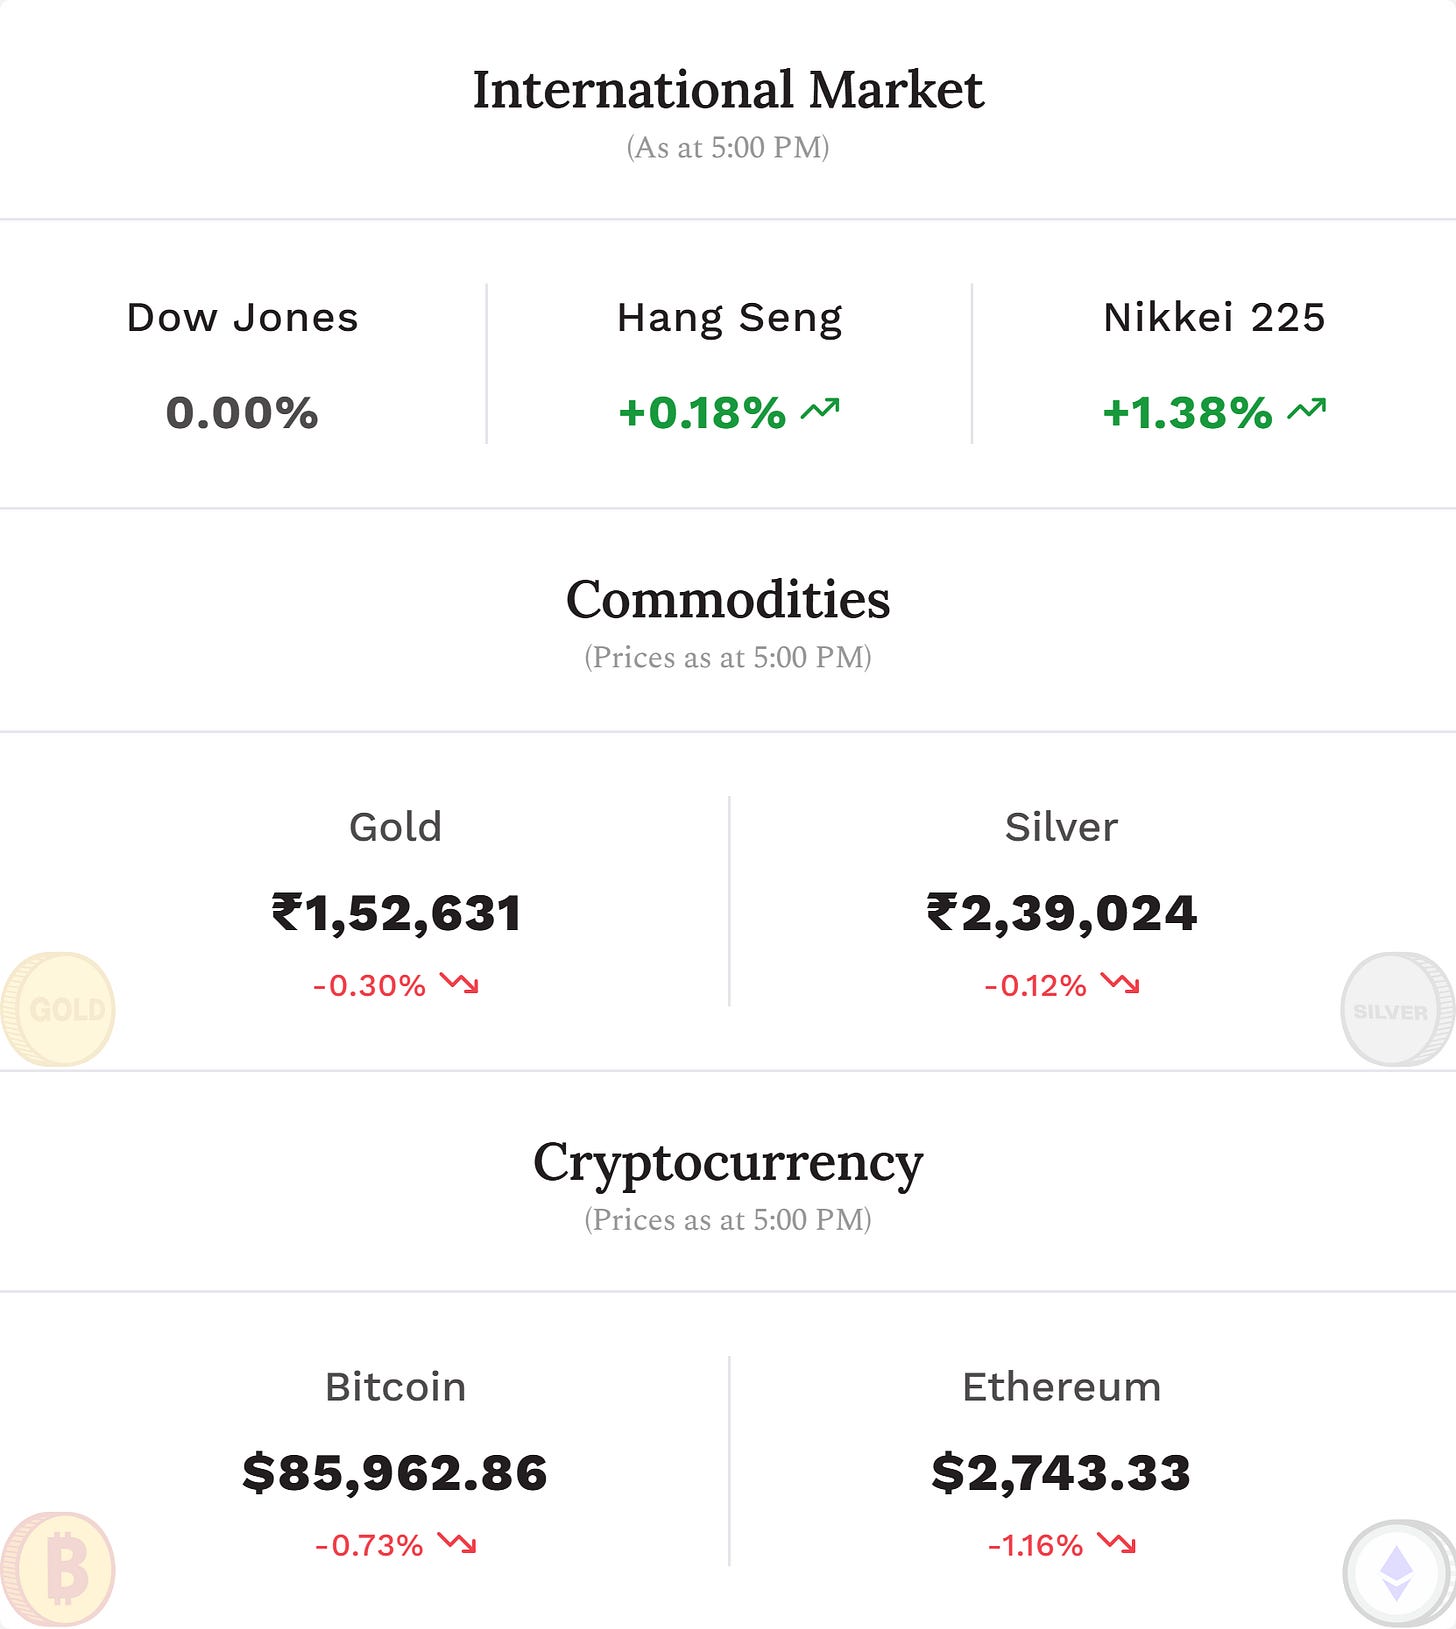
The Big Picture: Global sentiment improved as Strait of Hormuz crude and LNG flows reached a six-month high, while Saudi Arabia resumed exports through the waterway, helping Brent fall for the fourth consecutive session from above $107 to around $98. Diplomatic signals also strengthened, with Trump indicating the Iran war could end soon and potential talks with Iran, while the upcoming Trump-Xi summit could offer further clarity on US-China trade relations.
FII/DII Activity (September 21, 2026): Institutional flows remained mixed, with DIIs net buyers at ₹2,797 crore, while FIIs were net sellers at ₹576 crore, indicating stronger domestic buying support despite continued foreign outflows.
Watch Out For Tomorrow
IPO Corner: Varmora Granito IPO is open for subscription today, making the IPO robust sentiment.
Macro: India HSBC Manufacturing PMI Flash (Sep) & HSBC Services PMI Flash (Sep) data is scheduled to be released tomorrow.
Market Watch: Markets remained slightly negative as expiry-day volatility and lingering caution after last week’s rate hike kept buyers on the sidelines. However, easing crude prices and improving geopolitical signals suggest that macro conditions are becoming more supportive, providing signs of stabilisation rather than a clear rally.
Word of the day
Stabilisation: A phase when a falling or volatile market begins to find support and shows signs of holding at current levels, even without a strong recovery.